








FIFO (first in, first out) assumes your oldest inventory sells first, so older costs go into cost of goods sold (COGS). LIFO (last in, first out) assumes your newest inventory sells first, so the latest costs hit COGS. When prices rise, FIFO shows higher profit (and higher taxes), while LIFO shows lower profit (and lower taxes).
In retail, manufacturing, and wholesale, solid profits come from closely managed inventory. (Shocking, we know.)
FIFO and LIFO are two of the most common ways to value inventory. Pick one and it shapes your COGS, profit, and tax bill.
Here, we'll walk through FIFO vs. LIFO with real numbers, cover the tax and accounting rules, and help you decide which method fits your business.
Key Takeaways
- FIFO expenses your oldest costs first. LIFO expenses your newest costs first.
- When prices rise, FIFO means higher profit and higher taxes. LIFO means lower profit and lower taxes.
- US GAAP allows both methods, but IFRS doesn't allow LIFO.
- In the US, electing LIFO means filing IRS Form 970 and using LIFO in your financial reports too.
- FIFO is usually the simpler fit for perishables and for businesses selling internationally.
What Is FIFO?
FIFO stands for first in, first out. It's a method of inventory management and valuation in which goods produced or bought first are sold, used, or disposed of first. In other words, goods sell in the order they arrived.
For reporting, FIFO assumes the oldest costs go into COGS on your income statement, and newer goods stay in inventory. So when you sell a product using FIFO, its cost is the cost of your older goods. FIFO is one of the most popular inventory accounting methods.
Pros and Cons of FIFO
Pros of FIFO:
- It matches how stock really moves. Most businesses ship older stock first to avoid spoilage or a drop in value.
- Ending inventory reflects recent costs. Older costs leave first, so what's left on your balance sheet sits closer to current costs.
- It works almost anywhere. FIFO is allowed under both US GAAP and IFRS (more on that below).
Cons of FIFO:
- Higher taxes when prices rise. Older, cheaper costs hit COGS, so reported profit (and your tax bill) goes up.
- Margins can look rosier than reality. COGS reflects older costs, so profit may look better than what restocking costs you today.
FIFO Example
| Calculating FIFO profits |
| Profit = Selling price - Cost of oldest inventory |
With FIFO, you subtract your oldest purchase cost from the selling price to get reported profit. Let's put real numbers on it.
Say you buy 100 units at $10, then another 100 units at $12. You sell 150 units at $20 each, for $3,000 in revenue.
Under FIFO, the first 100 units sold carry the $10 cost ($1,000), and the next 50 carry the $12 cost ($600). That's $1,600 in COGS, $600 of ending inventory (50 units at $12), and $1,400 in gross profit.
It's the same math behind the basic cost of goods formula. If you track COGS in a perpetual inventory system, it simply happens with every sale.

What Is LIFO?
LIFO stands for last in, first out. It's a method of inventory management and valuation in which the goods produced or bought most recently are recorded as sold first. In other words, the cost of your newest products goes into COGS, while the cost of older goods stays in inventory.
Some US businesses choose LIFO when their costs keep rising, because matching the newest (higher) costs to current sales lowers reported profit and taxable income. US tax law lets you elect LIFO, as long as you play by its rules.
That matching is LIFO's big appeal. Your income statement reflects what inventory costs you right now.
Pros and Cons of LIFO
Pros of LIFO:
- Lower taxable income when costs rise. Your newest, priciest costs go into COGS, which trims reported profit.
- COGS reflects current costs. Your margins show what it actually costs to restock today.
Cons of LIFO:
- It's not allowed under IFRS. If you plan to expand abroad, LIFO may be off the table (more on that below).
- The conformity rule ties your hands. Use LIFO for US taxes and you generally must use it in reports to shareholders and lenders too.
- Ending inventory can get badly outdated. Old costs can linger on your balance sheet, far from what the stock is worth today.
- Recordkeeping gets heavier. You'll need to track LIFO "layers" of costs from different purchase periods.
- It's a poor fit for perishables. Leaving the oldest stock idle risks spoilage and piles on carrying costs.
LIFO Example
| Calculating LIFO profits |
| Profit = Selling price - Cost of newest inventory |
With LIFO, you subtract your most recent purchase cost from the selling price to get reported profit. When costs are rising, that lowers your reported profit.
Let's use the same numbers. The first 100 units sold carry the newest $12 cost ($1,200), and the next 50 carry the $10 cost ($500). That's $1,700 in COGS, $500 of ending inventory (50 units at $10), and $1,300 in gross profit.
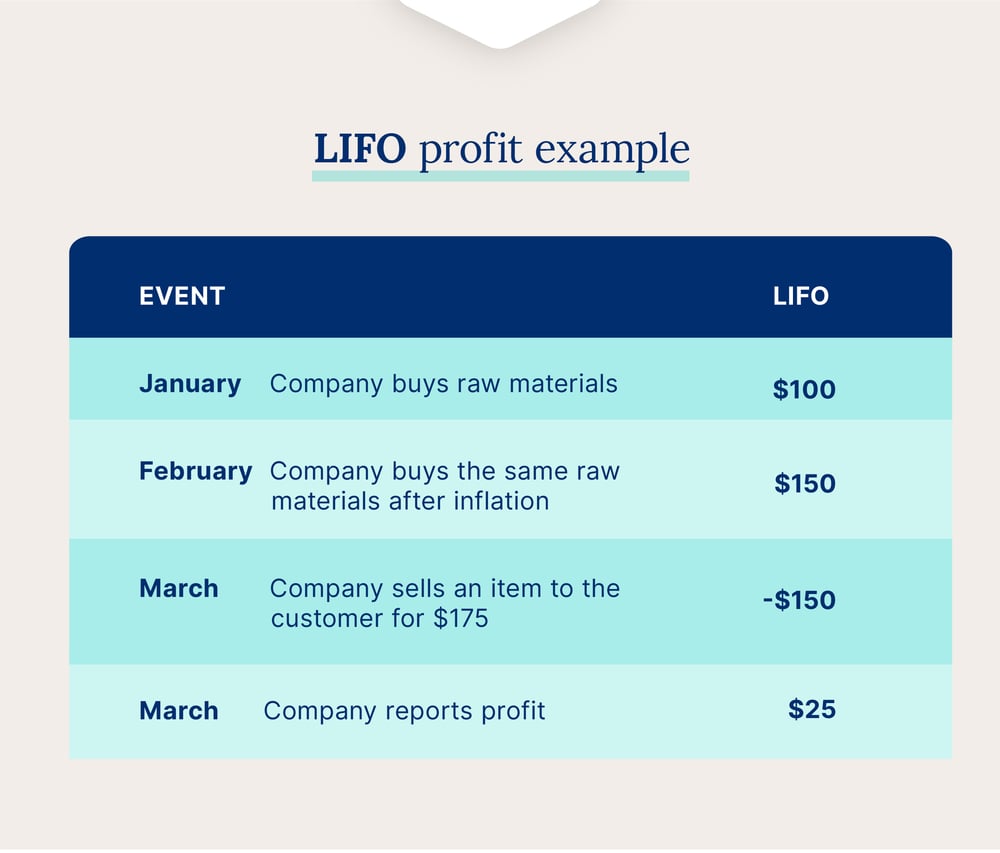
Here's how FIFO and LIFO stack up on the exact same sale:
| Buy 100 units at $10, then 100 at $12. Sell 150 at $20. | FIFO | LIFO |
|---|---|---|
| Revenue (150 units at $20) | $3,000 | $3,000 |
| COGS | $1,600 (100 at $10 + 50 at $12) | $1,700 (100 at $12 + 50 at $10) |
| Ending inventory (50 units) | $600 (50 at $12) | $500 (50 at $10) |
| Gross profit | $1,400 | $1,300 |
Same products, same sale, $100 difference in profit. Scale that across thousands of units and the gap gets real.
Key Differences Between FIFO and LIFO
FIFO and LIFO are the methods companies use to classify inventory and calculate profit. Your profit affects your income taxes and is a key measure of performance. Each method yields different profits, so it pays to know which one makes sense for you.
| FIFO | LIFO | |
|---|---|---|
| Meaning | Assumes the oldest products in inventory sell first | Assumes the last item purchased is the first one sold |
| Restrictions | No restrictions under GAAP or IFRS | Not allowed under IFRS |
| Recordkeeping | Simpler | More complex (track LIFO layers) |
| Impact when prices rise | Lower COGS and higher net profit | Higher COGS and lower net profit |
| Ending inventory value when prices rise | Closer to current costs | Can be badly outdated |
| Tax impact when prices rise | Higher taxes | Lower taxes |
| Matches physical flow | Usually yes | Usually no |
| Best for | Perishables, global sellers, most SMBs | US businesses with steadily rising costs |
If your ending inventory value drifts far from what your stock is worth today, it may be time to read up on inventory revaluation.
Practical Applications and Industry Suitability of FIFO and LIFO
Different industries get different mileage out of FIFO and LIFO, depending on what they sell and how their stock moves. Here's how each method lines up with real-world businesses.
FIFO in Perishable and Seasonal Industries
FIFO is a natural fit if you sell perishables or anything with an expiration date. Think:
- Restaurants and bakeries: Older stock gets used or sold first to avoid waste.
- Grocery stores: Fresh items move out in the order they arrive.
- Health and beauty brands: Products with a shelf life sell before they expire.
- Tech and electronics sellers: Older models sell before they become obsolete.
- Seasonal retailers: Last season's stock clears out first.
Selling goods with expiry dates? FEFO (first expired, first out) takes FIFO a step further by moving whatever expires soonest first. It's a staple for food and beverage businesses.
LIFO for Non-Perishable Goods
LIFO suits industries with durable, non-perishable inventory, where matching the latest costs matters most. Examples include:
- Oil and gas companies: Often use LIFO to match rising costs during inflationary periods.
- Retailers with durable goods: Can benefit from LIFO's tax advantages when costs are high.
Knowing how your industry tends to play it helps you pick the method that best supports your goals.
Which Method Is Better for Your Business?
In general, FIFO is the safer bet because both GAAP and IFRS allow it. LIFO can still pay off if you're a US business and your costs keep climbing. To decide, look at how your inventory costs are changing.
- If your costs are rising or likely to rise, LIFO can be better, because higher recent costs in COGS mean lower taxes.
- If your costs could drop soon, FIFO is usually the better option.
- If you want your balance sheet to reflect current costs, FIFO is the better option, since leftover inventory carries your most recent costs.
How fast your stock moves matters too. A high inventory turnover ratio means cost layers don't linger, so the FIFO vs. LIFO gap shrinks. Your priorities may also shift as you grow, so it's worth revisiting your choice as your business changes.

How FIFO and LIFO Affect Your Taxes
When prices rise, LIFO puts your newest, highest costs into COGS. Higher COGS means lower reported profit, and lower reported profit means lower taxable income. FIFO does the opposite, so you'll typically pay more tax in the short term.
There's a catch. Under the LIFO conformity requirement, using LIFO on your tax return means using it in reports to shareholders, partners, and lenders too. You elect LIFO by filing Form 970 with the IRS.
So, does the IRS require FIFO or LIFO? Neither. According to IRS Publication 538, you need a method that clearly reflects your income, and you need to use it consistently from year to year.
Want to change methods later? That's a change in accounting method, which generally needs IRS consent through Form 3115. Tax rules get specific fast, so loop in your accountant before you switch (and check out our tax season tips for SMBs).
What Is Inventory, and How Is It Valued?
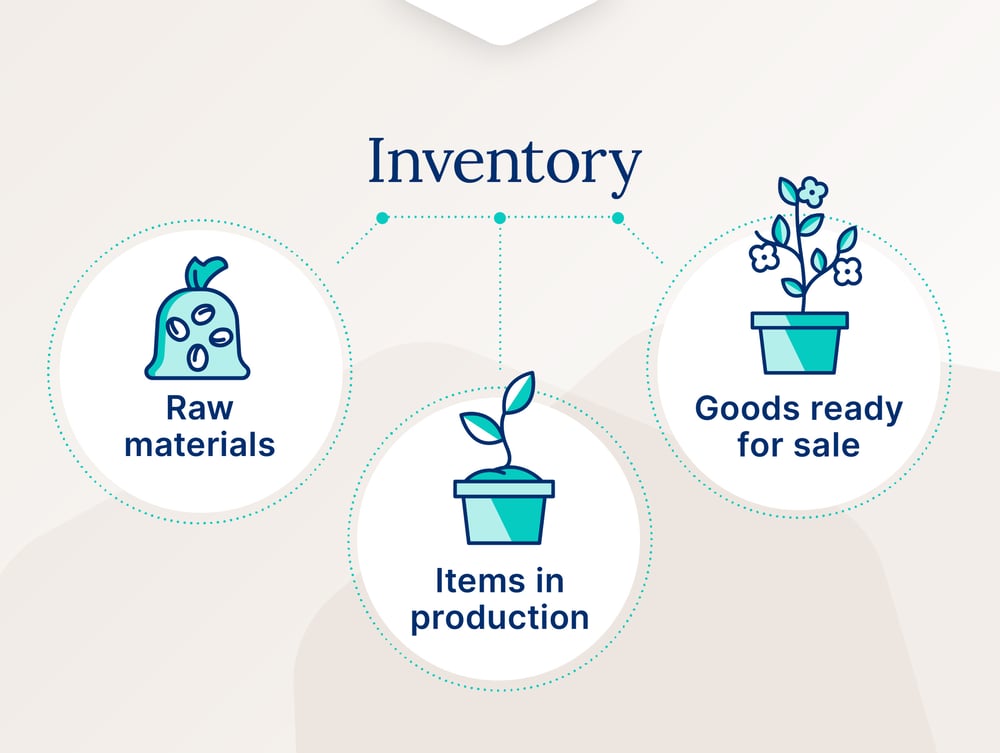
Inventory is the materials and goods that make up the products a company sells. Managing it well helps you track spending and value for tax and internal purposes. Generally speaking, inventory falls into three stages:
- Raw materials
- Items in production
- Goods ready for sale
Your accounting team may assign value to inventory and classify it as a company asset, since inventory can turn into cash soon. To value your company accurately, all your assets may need to be assessed.
At the beginning and end of the fiscal year, you should perform an inventory valuation. For valuation purposes, you must:
- Apply Generally Accepted Accounting Principles (GAAP)
- Clearly reflect your income
- Maintain consistency from year to year
GAAP is the standard set of accounting principles issued by the Financial Accounting Standards Board (FASB). GAAP allows both FIFO and LIFO. However, the International Financial Reporting Standards (IFRS) don't allow LIFO.
When your company records income and expenses, there are two methods:
- Cash accounting: Records transactions when invoices or bills are paid
- Accrual accounting: Records transactions when invoices or bills are created
Holding inventory doesn't automatically lock you into accrual accounting. Per IRS Publication 538, small businesses that meet the gross receipts test can generally use the cash method. Either way, following inventory control best practices keeps your numbers trustworthy.
GAAP and IFRS Rules for FIFO and LIFO
Generally Accepted Accounting Principles set the standards for accounting procedures in the United States. Under GAAP, both FIFO and LIFO are allowed.
However, IFRS standards issued by the International Accounting Standards Board (IASB) don't permit use of the LIFO method. Under IAS 2, you'd use FIFO or weighted average cost instead.
Outside the US, most countries follow IASB rules. That's why US-based companies using LIFO for local financial statements often use FIFO for overseas operations.
Thinking about LIFO? You'll need to file Form 970 with the IRS to elect it. Once you're on LIFO, US tax law expects you to stay on it unless the IRS approves a change.
How FIFO and LIFO Compare to Other Inventory Valuation Methods
FIFO and LIFO get most of the attention in inventory valuation chats. But you might also consider alternatives like weighted average cost and specific identification to better fit your needs.
Weighted Average Cost Method
This approach calculates the average cost of goods available for sale and applies it evenly to inventory sold and remaining stock. It's especially useful for:
- Businesses with identical products where tracking individual items isn't necessary
Specific Identification Method
This method assigns specific costs to individual items in inventory, making it ideal for:
- Companies dealing with unique, high-value items like luxury goods or custom machinery
By comparing these approaches, you can find the method that most accurately represents your inventory and financial performance.
Simplify Inventory Management With Cin7
Knowing how FIFO vs. LIFO works helps you choose the best inventory management techniques for your business and make the most of tax benefits. Both methods have pros and cons, so pick the one that suits you. If you operate internationally, FIFO is usually the way to go, since IFRS doesn't allow LIFO.
So where do we come in? Cin7 Core's costing methods include FIFO, FIFO by batch or serial number, FEFO by batch or serial number, and special (specific) batch or serial costing. Every sale pulls the right cost into COGS, no spreadsheet gymnastics required.
Our inventory and order management software supports better accounting and brings all your sales channels into one cloud-based platform. Cin7 products keep your sales channels, warehouse, and accounting software on the same page.
We integrate natively with QuickBooks Online and Xero, so your COGS lands in your books without retyping a thing.
Take Klein River Cheese, a family-owned artisan cheesemaker in South Africa that's been making cheese for more than two decades. It sells in person, through direct-to-consumer e-commerce, and B2B. With food safety and compliance on the line, the team needed accurate expiry date tracking across individual items and full batches.
With Cin7 Core, Klein River assigns manufacture and expiry dates, so the status of entire product lines is visible with minimal effort. Cin7 also syncs with Xero for accounting and with WooCommerce.
"From a food safety point of view, having data at the click of a button when it comes to your ingredients; your traceability; where your product is; when it leaves your facility; where it's being consumed, is critical," says manager Raymond Siebrits.
Ditch the spreadsheets and stop manual data entry. Start a free trial to see how Cin7's inventory and order management system helps you reach new markets!
FAQs About FIFO and LIFO
Looking for more on LIFO and FIFO? Here are our answers to your top questions.
Which Is Better, LIFO or FIFO?
For most businesses, FIFO. It's allowed under both GAAP and IFRS, it matches how stock usually moves, and your ending inventory reflects recent costs. LIFO can make sense if you're a US business with steadily rising costs and you want lower taxable income.
Why Would a Company Use FIFO?
FIFO matches the way most businesses physically move stock: oldest first. It's accepted under both GAAP and IFRS, keeps ending inventory close to current costs, and makes for simpler records.
Is LIFO or FIFO Better for Taxes?
When your costs are rising, LIFO usually lowers your taxable income because your newest, priciest costs go into COGS. FIFO does the opposite. But LIFO isn't allowed under IFRS, you elect it with Form 970, and the conformity rule means using LIFO in your financial statements too.
Is LIFO Allowed Under IFRS?
No. IAS 2 doesn't permit LIFO. Under IFRS, you'd use FIFO or weighted average cost, or specific identification for items that aren't interchangeable.
What's the Difference Between FIFO, LIFO, and Weighted Average Cost?
FIFO expenses your oldest costs first, and LIFO expenses your newest costs first. Weighted average cost blends everything into one average cost for both sold and remaining stock. In our example, that's $11 per unit ($2,200 for 200 units), so COGS lands at $1,650, right between FIFO and LIFO.
Can You Switch From LIFO to FIFO?
Yes, but it's not a quick toggle. Switching is a change in accounting method, which generally needs IRS consent through Form 3115. US tax law expects you to stay on LIFO unless the IRS approves the change, so talk to your accountant first.
Is LIFO Allowed in the USA?
Yes! LIFO is allowed under US GAAP and US tax law. You elect it by filing Form 970 with your tax return. Just remember the LIFO conformity rule: if you use LIFO for taxes, you'll need to use it in your financial reports too.
Why Don't More Companies Use LIFO?
For starters, IFRS doesn't allow it, so it's off the table if you report under those standards. In the US, the conformity rule means lower taxable profits also show up in the reports your lenders and investors see. LIFO also takes more recordkeeping, and it rarely matches how stock actually moves through your warehouse.
What Are the Four Main Types of Inventory?
They're raw materials, work in progress (WIP), finished goods, and MRO (maintenance, repair, and operations) supplies. You can dig into each one in our guide to inventory classification. Your valuation method matters across all of them, since raw material costs flow through WIP into the finished goods you sell.
What's the Difference Between FEFO and FIFO?
FIFO goes by receipt date, so the first stock in is the first stock out. FEFO (first expired, first out) goes by expiry date instead, so whatever expires soonest gets picked and costed first. That makes FEFO a smart choice for food, beverage, and health and beauty products, where nobody wants a surprise on the shelf. In Cin7 Core, you can use FEFO costing by batch or serial number, and those products need an expiry date.
More from the blog
View All Posts
What Is Cost of Goods Sold (COGS) + How to Calculate It
Read More
January Inventory Reconciliation: Fixing Cross-Channel Gaps Before Tax Filing Season
Read More